

Key Takeaways:
- Fannie Mae’s DU Update Removes Minimum Credit Requirements
Starting November 16, 2025, Fannie Mae removed the 620 minimum credit score requirement in Desktop Underwriter (DU). This change allows borrowers with limited credit history to qualify based on overall financial responsibility, income stability, and payment patterns. - VA Loans Offer Unique Benefits for Servicemembers and Veterans
VA loans provide 100% financing (no down payment), no private mortgage insurance (PMI), competitive interest rates, and a faster approval process. These features make homeownership easier and cheaper for eligible veterans, active-duty members, and surviving spouses to buy a home. - VA Loan Inspection Requirements Ensure Safe and Habitable Homes
While VA loans require an appraisal rather than a mandatory home inspection, properties must meet VA Minimum Property Requirements (MPRs). These include functional systems (electrical, plumbing, HVAC), safe foundations, proper drainage, adequate living space, and compliance with local building codes.
If you’re planning to buy a home with a VA loan, understanding how recent changes affect VA loan approvals is key. At Dream Home Mortgage, with 25 years of experience helping veterans and active-duty military members achieve homeownership, we guide borrowers through every step. VA loans offer unique benefits like 100% financing, no PMI, and competitive rates, making homeownership more accessible for those who served. Therefore, knowing the VA loan inspection requirements and industry updates can save you time and money. In this blog, you’ll learn about VA loan requirements, eligibility, inspection standards, and key matters that effect VA borrowers. We’ll also discuss the how Fannie Mae’s recent update reflects a broader shift in the industry as it may encourage more flexible evaluations for all kinds of first-time homebuyers.
Fannie Mae Removes Minimum Credit Score Requirements
Fannie Mae recently announced a significant policy change that affects many mortgage borrowers. Starting November 16, 2025, Fannie Mae removed the 620 minimum credit score requirement from Desktop Underwriter (DU) for new loan applications. This major change shows how the mortgage industry is moving to smarter risk checks. Instead of looking mainly at credit scores, DU now considers many factors to decide if a borrower qualifies. Even though, the Fannie Mae update directly impacts conventional loans, many lenders handle both types. Therefore, such policy changes often influence how lenders assess risk and flexibility across all loan programs, including VA loans.
What This Means for Borrowers
This change benefits borrowers with “thin credit files”—those with limited credit history despite strong finances. Therefore, instead of disqualification based solely on credit scores, the system now evaluates:
- Complete income and employment stability
- Bank account management and savings patterns
- Payment history on non-traditional accounts
- Overall financial responsibility indicators
FHFA Director Bill Pulte confirmed that loan rules haven’t changed. Only the credit scoring method is updated. This update challenges FICO’s control and could lower costs for borrowers. Our experts say it gives responsible borrowers who were excluded due to limited credit history a new chance.
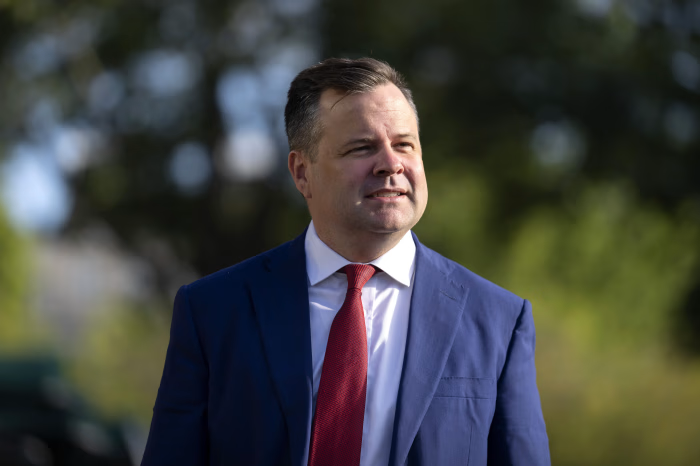
Federal Housing Finance Agency Director Bill Pulte Mark Schiefelbein/Associated Press
The Power of VA Home Loans
VA home loans are among the most beneficial mortgage programs for servicemembers, veterans, and their families. Therefore, unlike conventional mortgages, VA loans make homeownership more accessible and affordable.
- 100% Finance Coverage means no down payment is required, helping buyers secure homes without needing large savings.
- No Private Mortgage Insurance (PMI) eliminates extra monthly costs that conventional loans charge when the down payment is under 20%, saving borrowers hundreds of dollars monthly.
- Competitive Interest Rates offer some of the best market terms since the Department of Veterans Affairs backs part of the loan, reducing interest costs and saving thousands over time.
- Rapid Approval Process at Dream Home Mortgage ensures a fast turnaround.
VA Loan Eligibility Requirements
The U.S. Department of Veterans Affairs sets clear rules for who can get VA home loan benefits. We made a list of requirements that you can use as a checklist to determine if you’re eligible for this loan option:
Service Requirements for Eligibility
To qualify for a VA loan, you or your spouse must meet at least one of these service thresholds:
- Wartime Service: 90 consecutive days of active service during officially recognized wartime periods
- Peacetime Service: 181 days of active service during peacetime
- National Guard or Reserves: More than 6 years of service
- Surviving Spouse: Married to a servicemember who died in the line of duty or from a service-connected disability
According to a 2022 Navy Federal Credit Union survey, nearly 15% of servicemembers who recently obtained non-VA mortgages weren’t aware they qualified for VA loan benefits. This lack of awareness costs veterans thousands in potential savings, highlighting the importance of understanding your earned benefits. Your VA loan DTI also affects approval. Many first-time homebuyers ask: Can I get a VA loan with 55 DTI? While lenders prefer under 41%, VA loans allow flexibility. A 55% VA loan DTI isn’t automatic disqualification if you have strong residual income, good credit history, and stable employment. At Dream Home Mortgage, we review your full financial profile, not just your VA loan DTI, to improve approval chances.

VA Loans and Spouses: Who Qualifies and How It Works
Our team tends to get questions about VA loan spouse requirements all the time as they are very common. Therefore, the answers vary based on your relationship to the qualifying veteran.
- Can a Spouse Use a VA Loan?
Yes. If you’re married to an eligible veteran or active-duty servicemember, you can buy a home together using a VA loan with spouse. Both names can be on the loan and title, and combined incomes may help you qualify for a larger amount. - Non-Spouse Co-Borrowers
Can a non spouse be on a VA loan? Yes, but only the veteran’s share of the loan gets VA guarantee benefits. This setup may affect the interest rate or require a down payment. - Spouse-Only Applications
Can a spouse apply for a VA loan alone? Usually not, unless they qualify as a surviving spouse. Surviving spouses of servicemembers who died in duty or from service-related disabilities may be eligible for military spouse loans.
Those seeking extra funds beyond home loans can check out personal loans for military spouses, which have different terms and purposes.
Steps to Buying a House with a VA Loan
You can plot a course with steps to buying a house with a VA loan more smoothly when you understand each phase, helping you avoid unnecessary delays. Our experts made a step-by-step guide of the complete process of buying a house with VA loan financing.
1. Obtain Preapproval
You can begin by securing preapproval from a qualified VA lender. This critical first step establishes your budget and demonstrates to sellers that you’re a serious, qualified buyer. We’ll review your financial situation, verify your eligibility, and provide a preapproval letter. Get Prequalified Now!
2. Secure Your Certificate of Eligibility (COE)
Your COE confirms your military service and validates your VA loan eligibility. We can help you obtain this certificate through the VA’s Web LGY system, or you can request it directly through VA.gov. Your COE is essential documentation that must accompany your loan application.
3. Begin Your Home Search
Work with a knowledgeable real estate agent who understands VA loan requirements and VA loan inspection requirements. Focus on properties that meet VA Minimum Property Requirements (MPRs) to avoid potential approval complications.
4. Submit Your Purchase Offer
When you find the right property, submit a purchase offer that includes a VA option clause. This protective provision allows you to withdraw from the contract without penalty if the property appraises below the purchase price.
5. Complete the VA Appraisal
Your lender will order an appraisal from a VA-certified appraiser who will determine the property’s fair market value and verify it meets VA MPRs. This appraisal protects both you and the VA by ensuring the property represents sound collateral.
6. Arrange for Home Inspection
While not required, we strongly recommend hiring a professional inspector to conduct a thorough va home loan inspection. This examination goes beyond the appraisal’s scope, identifying potential issues with electrical systems, plumbing, roofing, HVAC equipment, and structural components.
7. Proceed to Closing
After completing all inspections and meeting loan conditions, you’ll sign closing documents and receive your keys. Congratulations, you’re now a homeowner!
Definitive Guide to VA Loan House Inspection Requirements
You have to understand that VA loan house inspection requirements is key to a smooth homebuying process. The VA sets these rules to make sure veterans don’t buy unsafe or unsuitable homes.
VA Minimum Property Requirements (MPRs)
The Department of Veterans Affairs maintains specific va home loan inspection requirements that properties must satisfy. These MPRs make sure that your home is safe, structurally sound, and sanitary. Here’s your va home loan inspection checklist:
Essential Systems and Components:
- Functional electrical, heating, and cooling systems
- Adequate roofing with sufficient remaining lifespan
- Proper water supply and sanitary facilities
- Safe sewage disposal system
- All-weather access via public or private roads
Safety Requirements:
- Freedom from lead-based paint hazards
- No wood-destroying insects, fungus, or dry rot
- Adequate drainage prevents water accumulation
- Stable foundation without significant settlement issues
- Properly ventilated attics and crawl spaces
Habitability Standards:
- Sufficient square footage for comfortable living
- Facilities for sleeping, cooking, and maintaining hygiene
- Compliance with local building codes
- Proper zoning for residential use
How to Get Your Certificate of Eligibility (COE)?
Your COE is fundamental to accessing VA loan benefits. Therefore, you can request this documentation through three methods:
- Online (Fastest Method): You can request it directly from the VA portal at VA.gov. If your service records are digitized, you’ll typically receive your COE within minutes.
- Through Your Lender: We can obtain your COE using the VA’s Web LGY system. It is the most convenient as we handle the entire process.
- By Mail (Slowest Method): Complete VA Form 26-1880 and mail it to your regional loan center. This method takes considerably longer but remains available if electronic access isn’t feasible.
Required Documentation
The documents you’ll need vary based on your military experience:
- Active Duty Service Members: Statement of Service signed by your commanding officer, including full name, Social Security number, birth date, entry date, and any lost time periods.
- Veterans: DD Form 214 (discharge or separation papers).
- Activated National Guard/Reserve Members: DD Form 214 or equivalent discharge documentation.
- Never-Activated National Guard/Reserve Members: Statement of Service showing at least 6 years of creditable service.
- Surviving Spouses: Veteran’s DD Form 214, marriage license, and either DIC documentation or completed VA Form 21P-534EZ with death certificate.

Why Choose Dream Home Mortgage?
Since 1998, Dream Home Mortgage has helped veterans achieve their homeownership dreams. As part of Brazos National Bank, we combine financial stability with personalized service tailored to military families. We’re registered in all 50 states and, as an FDIC-insured Equal Housing Lender, provide fair access to mortgage financing. Led by Hussein Panjwani (NMLS ID 334616), our experienced team specializes in VA lending and veteran services. With our efficient process, many loans are approved fast, helping you secure your home quickly. Your service has earned you exceptional benefits so let us help you maximize them. You can book your free consultation session today and start your journey toward a VA-backed dream home with 100% financing, no PMI, and competitive rates.
For instant updates follow Dream Home Mortgage on social media handles. 


FAQs:
Technically, a VA loan does not require a separate home inspection. However, the VA mandates only an appraisal. A VA home loan inspection typically costing $300–$500, can uncover hidden structural defects, plumbing problems, or HVAC issues, potentially saving you thousands.
Sellers must ensure their property meets VA Minimum Property Requirements (MPRs) before closing. Following VA loan inspection requirements for sellers can prevent delays and help the property pass appraisal smoothly.
Yes, military spouse loans exist to support spouses of eligible servicemembers. These can include VA-backed options or personal loans for military spouses to assist with housing, relocation, or other financial needs.
Yes. Fannie Mae will eliminate the 620 minimum credit score requirement in DU for new loan casefiles starting November 16, 2025. DU will now use a comprehensive risk analysis instead of relying solely on minimum credit score requirements.
On VA loans, a seller or builder may pay all allowable closing costs and provide additional “seller concessions” up to 4% of the home’s reasonable value (VA appraisal/Notice of Value). Closing-cost credits do not count toward this 4% cap.
