
Quick Answer:
580 is often the starting credit score associated with FHA loans using a 3.5% down payment, although borrowers with lower scores may have limited options and stricter requirements. Mortgage approval with bad credit depends on more than the score: lenders also evaluate income, debts, payment history, reserves, down payment, and the specific loan program.
Key Points
- Bad Credit Doesn’t Mean No Mortgage
A 580 credit score is typically considered “bad,” but you can still qualify for a home mortgage loan through specialized programs like FHA, VA, or USDA loans, or by working with non-traditional lenders. - Lenders Look Beyond Credit Scores
Even with a low score, factors like a larger down payment, cash reserves, and a low debt-to-income ratio can improve your chances of mortgage application approval. - Government Programs & Assistance Can Help
First-time buyers with bad credit can benefit from government-backed loans and over 2,500 down payment assistance programs available across the U.S.
We know that buying your first home is exciting, but it can feel scary if your credit isn’t perfect. If you’ve been wondering whether someone with bad credit can get a mortgage loan, then the short answer is yes, it’s possible! It may be a little harder, and it may cost more, but it can still happen. With Dream Home Mortgage by your side, we can help you take the right steps and find low credit home loans that are perfect for you. In this article, we are going to understand what exactly home loans for bad credit are and walk you through everything you need to know. We will offer real examples and smart tips to help you understand how to get a mortgage with bad credit.
Reviewed by Dream Home Mortgage Team
Our mortgage specialists help borrowers understand available home financing options, including solutions for buyers with less-than-perfect credit. Mortgage approval depends on individual financial circumstances, loan program requirements, credit history, income, and other qualifying factors.
Bad Credit Mortgage Loans: What You Need to Know
Many borrowers search for bad credit mortgage loans approval because they are concerned about qualifying for a home loan with a lower credit score. While no mortgage lender can guarantee approval without reviewing a borrower’s complete financial situation, there are mortgage programs that may help qualified borrowers with less-than-perfect credit.
Approval depends on several factors, including credit score, income, employment history, debt-to-income ratio, down payment, and the type of mortgage program selected. Borrowers with bad credit may still have options through programs designed to provide more flexible qualification requirements.
What Is Considered “Bad Credit” in the Mortgage Industry?
Your credit score is a number that shows lenders how risky it is to loan you money. It ranges from 300 to 850. The higher your score, the better.
Here’s a basic breakdown of credit scores:
- 800 to 850: Excellent
- 740 to 799: Very Good
- 670 to 739: Good
- 580 to 669: Fair
- 300 to 579: Poor
A bad credit score is usually anything below 620. That doesn’t mean you can’t buy a mortgage loan. It just means it may take more work, and we offer specialized home loans for bad credit to help you out!
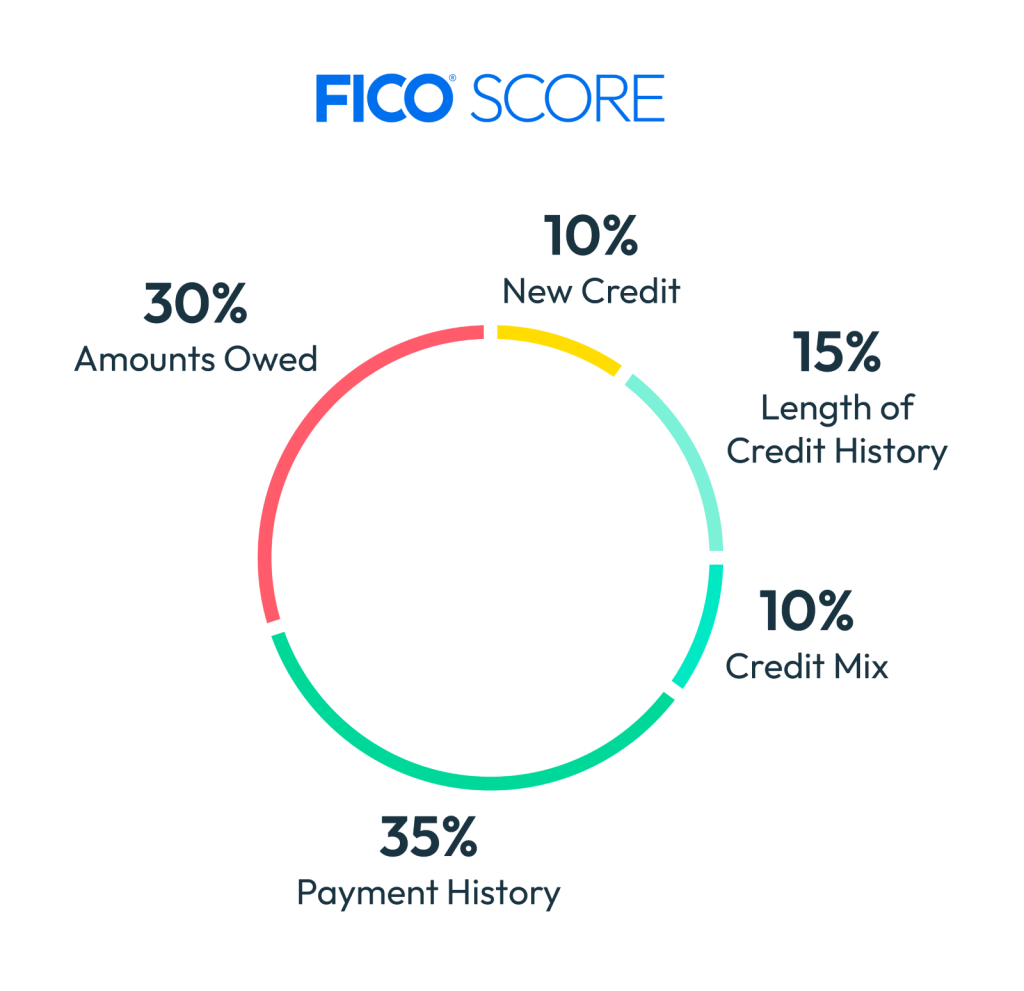
source: MyFico
Don’t Worry, You’re Not Alone!
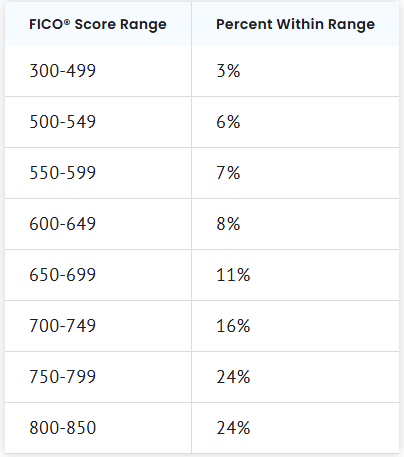
Did you know that many Americans don’t have perfect credit? In fact, you’ll be surprised to know that:
- About 15% of people have scores between 500 and 599.
- Another 10% have scores between 600 and 649.
That means 1 in 4 people fall into the “fair” or “poor” credit range. Therefore, if your score isn’t high, don’t worry, you’re not the only one! . Fortunately, there are mortgage lenders for bad credit who specialize in helping buyers with less-than-stellar scores. Some even offer guaranteed mortgage approval with bad credit through tailored programs that consider more than just your credit score. The average FICO score for 2025 is 715, and only 24% of Americans have a FICO score of 800 or above. Therefore, the vast majority of first-time home buyers have less-than-stellar credit scores.
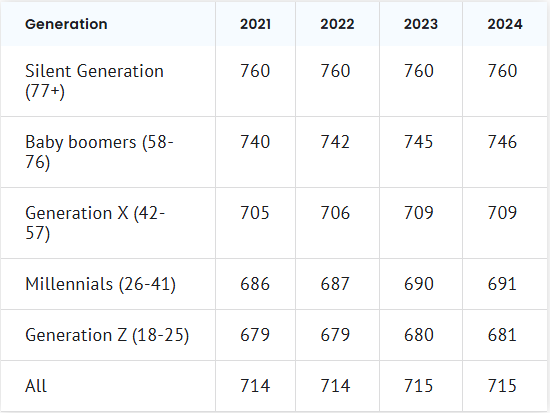
What is the Average Credit Score by Age?
Older Americans usually have better credit scores than younger people. For example, the silent generation has an average credit score of 760, while Gen Z has an average of 681. We have seen that baby boomers and the silent generation are the only groups with scores in the “very good” range. Gen X, millennials, and Gen Z all have scores in the “good” range. One reason older people have higher scores is that they’ve had credit for a longer time. A long credit history helps boost your score. Older people also often have different kinds of credit, like a car loan or a mortgage, which helps raise their score, too.
Can I Get a Mortgage With Bad Credit and It’s Cost?
Your credit score affects the interest rate on your low-credit home loans. This is the extra money you pay to borrow the mortgage loan. Now, to put things in perspective, let’s look at an example for a $300,000 loan:
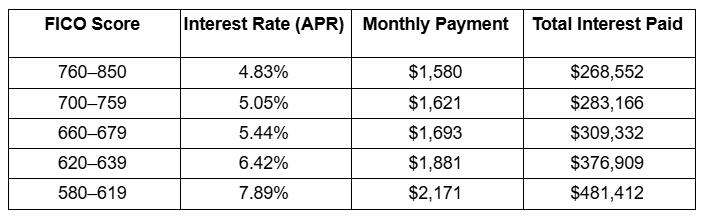
Do you see the difference? A lower score means you will have to pay more interest. It can sometimes be worth up to $100,000 if you opt for 30-year home loans for bad credit. These can vary by lender, location, and loan types.
But Rent Isn’t Cheap Either!
Even if your mortgage costs more because of your credit, it can still be better than paying rent. A 2024 report by Redfin (source) shows that half of U.S. renters are struggling to pay their rent on time. At least with a mortgage, you’re building equity in a house that you own. Plus, with rent prices going up, it might still make sense to buy, even with a higher interest rate. The perks of buying your own home greatly outweigh the cost burden of renting a space with periodic spikes. Therefore, you should get in touch with our licensed mortgage lenders today and look into our specialized home loans for bad credit.
What Lenders Look for Other Than Your Score?
Lenders will definitely look at more than just your credit score. Here are three things that can help you get approved, even if your score is low:
- A Big Down Payment: If you can pay more big down payment upfront, lenders may feel more comfortable giving you a loan. The best part is that if you pay a 20% down payment upfront, then you don’t have to pay Private Mortgage Insurance (PMI).
- Cash Reserves: This means money cash reserves in savings. It shows lenders that you can still make payments even if something unexpected happens.
- Low Debt-to-Income Ratio (DTI): This is how much money you owe each month compared to how much you make. Maintaining good habits with existing credit, such as timely credit card payments.
These strengths can boost your mortgage application, even if your credit score is low.

How to Qualify for Home Loans for Bad Credit?
If you have made up your mind to buy a home in 2025, then here are some ways to make it happen:
Shop Around
Not all lenders are the same. Some are open to mortgage approval with bad credit, while others aren’t. Compare offers.
Try Online and Non-Bank Lenders
Non-traditional and online lenders may offer more flexible terms, including mortgage no credit check programs but always do your due diligence.
What loan options exist for bad credit?
Some loan types are built to help first-time or low-credit buyers:
- FHA Loans: The Federal Housing Administration has designated low credit home loans. You can get one with a score as low as 500 (with 10% down) and even 580 (with 3.5% down).
- VA Loans: This home loans for bad credit are made for veterans and active military personnel and their family. If you are a vet or actively serving, then you don’t need to have any minimum credit score and no down payment.
- USDA Loans: For first-time home buyers who seek a peaceful living space and want a more rural pace of life. With USDA loans, you pay 0% down payment and get flexible credit rules.
Consider a Co-Signer
If a family member or friend with good credit co-signs, it can help you qualify. However, they will be responsible if you can’t make payments. Therefore, you need to be on top of your payment schedule so as to not burden your co-signer and stay in their good graces as well.
How much down payment do I need with bad credit?
In a recent survey, half of aspiring first-time homebuyers can’t afford to pay their down payment, as they lack the funds. Therefore, to help such homebuyers, there are over 2,500 down payment assistance programs in the U.S. You might qualify for one and not even know it!
Avoid “Too Good to Be True” Offers
Be cautious of lenders advertising guaranteed mortgage no credit check or “100% approval” claims. Some places promise “guaranteed approval” no matter your credit. You need to be careful! If it sounds too easy, it could be a scam or cost you way more later. With Dream Home Mortgage, you don’t have to worry about such scams, as we are a registered division of Brazos National Bank!
How do I improve my chances of approval?
You can boost your chances of home loans for bad credit approval by making smart financial moves. Here are some easy-to-follow tips that can make a big difference:
Check Your Credit Report
You can start by visiting AnnualCreditReport.com. You can get your free credit reports from the three major bureaus: Experian, Equifax, and TransUnion. Go through them carefully to spot any mistakes, such as incorrect account balances, late payments you didn’t make, or accounts you don’t recognize. You will have to get in touch with the bureaus to get them corrected.
Set a Realistic Budget
Everyone dreams of a villa by a lake with a hanging willow tree, but sometimes that’s not practical. You need to take a close look at how much you earn and where your money goes each month. You have to map out your budget by writing down your income, expenses, and debt payments. Budgeting helps you avoid overspending and manage your debt better, both of which are important when you are applying for home loans for bad credit.
Pay Your Bills on Time
Your payment history is one of the biggest factors that impact your credit score. Late payments can hurt your score quickly, even if it’s just one. Therefore, you need to make sure all your bills are paid on time.
Start Saving Now
You might be surprised to know how impactful small savings can be! Therefore, you can start by putting aside $400 to cover small emergencies and build up from there. A steady savings habit not only protects you in a financial crunch but also shows lenders you’re financially responsible.
Avoid Big Credit Moves
If you are looking to buy a house in the upcoming months, then you should hold off on any large purchases before applying for a mortgage. You also need to avoid closing or opening new credit accounts. These actions can definitely affect your credit score. It’s best to keep your accounts steady until after you’ve closed on your new home.
6 Best Cities in Texas for Buyers With Bad Credit
| City | Best Suited for Bad Credit Buyers |
|---|---|
| Houston | Subprime lenders, FHA, and VA loans |
| Dallas | FHA programs, down payment assistance |
| San Antonio | USDA loans, first-time buyer incentives |
| New Braunfels | FHA-friendly new builds, flexible credit options |
| McKinney | Low-credit VA and FHA loan access |
| Austin | City grants, FHA loans, and non-traditional lenders |
Frequently Asked Questions About Bad Credit Mortgage Loans
Can I get a mortgage with bad credit?
Yes, some borrowers with bad credit may still qualify for mortgage financing. Lenders review multiple factors, including income, employment history, debt-to-income ratio, credit history, down payment, and available loan programs when determining eligibility.
Are bad credit mortgage loans guaranteed approval?
No mortgage lender can guarantee approval before reviewing a borrower’s complete financial profile. However, borrowers with lower credit scores may have mortgage options depending on their financial situation and the loan programs available.
What credit score is needed to buy a house with bad credit?
The minimum credit score required depends on the loan program and lender requirements. Some mortgage programs may allow borrowers with lower credit scores to qualify, while stronger credit profiles may provide more financing options.
How can I improve my chances of getting approved with bad credit?
Borrowers can improve their approval chances by reducing existing debt, improving their credit history, saving for a larger down payment, maintaining stable income, and exploring mortgage programs that fit their financial situation.
Get in Touch Today and Overcome Bad Credit Hurdles
Yes, getting a mortgage with bad credit can be tough. However, with Dream Home Mortgage by your side, it’s not impossible. You can get approved for mortgage loans with a credit score as low as 580. You can also turn your dream into a reality by simply getting in touch with us by booking our free 30-minute consultation session. In this one-on-one session, we’ll advise and help you better understand home loans for bad credit. With over 27 years of experience, under the capable leadership of Hussein Panjwani, we have assisted thousands of first-time homebuyers in turning their dreams into reality!
In Short
- 💠 Qualify with credit as low as 580
- 💠 Use FHA, VA & USDA loan options
- 💠 Boost approval with a big down payment
- 💠 Access 2,500+ down payment programs
- 💠 Compare lenders for better terms
- 💠 Avoid scams—work with licensed pros
For instant updates follow Dream Home Mortgage on social media handles. 


Disclaimer: Mortgage approval is not guaranteed and depends on borrower qualifications, including credit history, income, employment, debt-to-income ratio, assets, and applicable lending requirements.
Yes, it’s possible. FHA loans allow applicants with scores as low as 500 (with a 10% down payment) or 580 (with 3.5% down). VA and USDA loans also offer flexible credit requirements, depending on eligibility.
Typically, yes. Lower credit scores usually come with higher interest rates, which can significantly increase your monthly payment, and the total interest paid over the loan term. However, with us you could get better interest rates on your loans.
You can increase your odds by paying your bills on time, saving for a larger down payment, checking your credit report for errors, and maintaining a low debt-to-income ratio.
Yes! There are more than 2,500 down payment assistance programs in the U.S. You can check out our Down Payment Assistance Program and get Down Payment Assistance up to $15,000!
It can be, but you must be cautious. Avoid lenders that promise “guaranteed approval” without checking your financials—it could be a scam. Always work with licensed lenders such as Dream Home Mortgage for a secure and transparent process.

yes we can get the mortgage even having low credit score
A realistic look at homeownership with a lower credit score. The distinction between ‘bad credit’ and ‘ineligible’ is crucial many first-time buyers mistakenly rule themselves out without exploring FHA, VA, or USDA options. While the article notes that interest rates are higher with lower scores, it correctly emphasizes that building equity often outweighs the cost of renting in the long term. For those navigating these hurdles, proactive financial planning and utilizing DPA programs are the best paths forward.
Best Article I’ve read these days very useful information
Thanks for sharing your thoughts! Have questions about your mortgage options? Schedule a free consultation with Dream Home Mortgage for expert guidance